WILL UPI MDR ADD EXTRA COST TO YOUR MONTHLY SIPS? PLAN TYPE AND INVESTMENT MODE MATTER, SAY EXPERTS
Merchant Discount Rate (MDR) is a fee charged for processing certain digital payment transactions. It is paid by the merchant rather than directly by the consumer.
Recently, the government has created an enabling framework under which MDR on UPI could be introduced. While the final rules and applicable transaction categories are yet to be clarified, the move could have implications for mutual fund investors.
How could UPI MDR affect the costs of direct and regular plans?
According to Siddharth Maurya, Managing Director, Vibhavangal Anukulkara Pvt Ltd, “the impact would depend more on who collects the UPI payment, who covers the MDR initially, and how the MDR is recovered.”
Protima Dhawan, Director & Unit Head, Anand Rathi Wealth, said, “Investments made directly through an AMC platform or its payment partner could initially bear the MDR. If an investor uses a broker, distributor or wealth platform, the intermediary or its payment partner could similarly bear the cost, depending on the payment arrangement.”
Shams Tabrej, Co-founder & CEO, Ezeepay (MJ Digital Services), observed, “MDR would not automatically increase a mutual fund's expense ratio. It is a payment-processing cost rather than a fund-management cost.”
Tabrej added that if an AMC absorbs the charge, a direct-plan investor may not see any additional cost. If the charge is passed on as a convenience or payment fee, however, the investor could face an additional cost.
For regular-plan investors, distributors already operate with commission and other operating costs, so the additional payment expense could affect their servicing economics.
How could UPI MDR affect SIP and lump-sum investments?
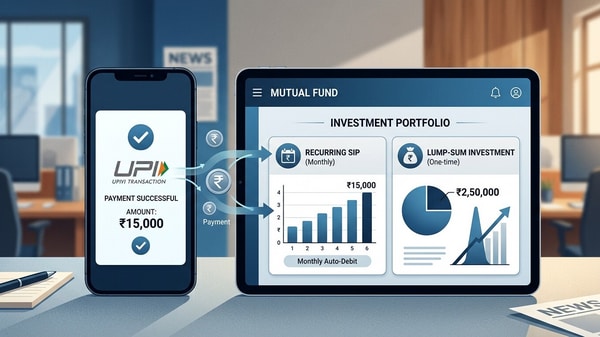
Tabrej explained that “the key difference for SIPs is the frequency of UPI payments. A monthly SIP involves a recurring payment, so even a small MDR could add up over the year if the cost is passed on to the investor”.
“If a hypothetical MDR of 0.5% were charged on every UPI collection, the investor would pay ₹25 per SIP instalment, or ₹300 over 12 months. In comparison, a ₹1 lakh lump-sum investment would generally involve one transaction. At the same hypothetical 0.5% MDR, the charge would be ₹500,” Maurya pointed out.
Tabrej said that “if the framework applies MDR to eligible merchant transactions above ₹2,000, a ₹2,001 payment could potentially fall into the chargeable category, depending on the final rules, merchant category and exemptions.”
Dhawan added that “under the current notified proposal, both SIP and lump-sum investments made through UPI could potentially be affected if the transaction falls within the eligible category and exceeds the proposed ₹2,000 threshold”.
However, Maurya cautioned that the actual impact will depend on how MDR is structured—whether it is charged as a percentage of the transaction, as a fixed amount, or based on a threshold.
He explained that a fixed ₹5 MDR would have a greater relative impact on a ₹1,000 investment than on a ₹50,000 investment. If MDR is percentage-based, the rupee cost would rise with the investment amount, although its percentage impact would remain the same.
Dhawan noted that “UPI is not the only payment option available to mutual fund investors". Depending on the platform, investors can also use NEFT, RTGS and net banking.
Says Dr VK Vijayakumar, Chief Investment Strategist, Geojit Investments, “Around 45% of new SIPs will be impacted. As far as lump sum investments are concerned, the UPI share is low at around 10%. If the new proposal is implemented, investment through UPI will move away to banks.”
Does the impact vary by investment platform?
Yes. Dhawan said “the impact could differ across AMCs, brokers, distributors and wealth platforms because the entity processing or receiving the payment may initially bear the MDR. Investors may not immediately see a separate charge, but absorbing the cost across a large number of transactions could put pressure on platform margins.”
Tabrej added that “an AMC with high transaction volumes may absorb a small MDR, while a broker or wealth platform could eventually recover it through payment or service fees. Distributors may also reassess their servicing economics.”
Maurya outlined three possible outcomes:
- Platform absorbs the MDR: Investors see no separate charge, but the platform's margins take the hit.
- Direct pass-through: Investors are charged a transaction or convenience fee.
- Indirect recovery: Platforms could adjust other fees, reduce cashback or promotional benefits, or change pricing structures.